

Reports over recent weeks that Vietnam may be considering the issuance of USD-denominated government bonds in international markets have drawn widespread investor attention.
In an update released on September 18, the Ministry of Finance (MoF) said the planned international investor meetings are intended solely for information-sharing and market outreach, with no bond offering or issuance attached to them. The non-deal roadshow (NDR) is expected to provide investors with information on Vietnam’s socio-economic conditions, fiscal and monetary policies, and public debt management orientation. The MoF will also gather market feedback and assess investor interest in local government bonds.
Nevertheless, from a policy perspective, preparations for an international bond issuance are in place. The 2026 public borrowing and debt repayment plan, approved by the Prime Minister, sets a maximum government borrowing level of VND969.796 trillion ($37.3 billion), with funding to be mobilized through a combination of domestic government bonds, overseas official development assistance (ODA) and concessional loans, international government bonds, and other lawful sources. The plan also requires the MoF to develop an international bond issuance proposal so that it is ready when funding is needed.
Transaction design
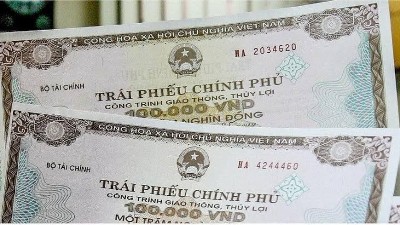
Vietnam already has a relatively comprehensive legal framework for issuing government bonds in international capital markets under the Law on Public Debt Management and Decree No. 95/2018/ND-CP, which governs the issuance, registration, custody, listing, and trading of government debt instruments in international markets.
Under the regulations, the MoF is required to base its international bond issuance proposal on the public borrowing and debt repayment plan, State budget estimates, and international financial market conditions before submitting it to the government for approval. The proposal must specify the necessity of the issuance, amount, currency, maturity, issuance market, and related costs.
The process also requires an assessment of the sovereign credit rating, preparation of documentation in accordance with applicable laws and international practices, pre-issuance investor meetings, and the selection of an experienced lead manager. Notably, the terms and interest rates for each issuance are determined based on advisory input and prevailing market conditions.
Thus, beyond determining funding needs and the amount to be raised, a key consideration is selecting the appropriate structure, market, and timing to optimize the cost of capital and related expenses, while ensuring sufficient scale and liquidity for the transaction to serve as a market reference. A well-traded USD-denominated government bond could help establish a benchmark yield curve, supporting the pricing of international loans and bonds issued by Vietnamese banks and companies.
This was also the approach Deutsche Bank experts discussed with the MoF in 2022. Regular government participation in international bond markets could not only diversify the investor base but also help establish a benchmark yield curve for Vietnam, providing a pricing reference for companies raising capital internationally. Therefore, a successful inaugural transaction should aim for sufficient scale, an appropriate maturity, a diversified investor base, and strong liquidity, rather than simply maximizing the amount of capital raised.
International experience
Recent experience shows that international bond issuances are not solely about meeting funding needs; they can also be used to establish and maintain benchmark points along the yield curve.
In January 2026, Mexico issued $9 billion in USD-denominated bonds across three maturities of eight, 12, and 30 years, attracting orders of up to $30 billion from 279 investors. According to Mexico’s Ministry of Finance, the transaction created three new liquid benchmark points on the government’s USD bond curve, supporting future access to capital for Mexican issuers.
Malaysia also issued $1.5 billion in Global Sukuk in July this year, with orders reaching 4.7-times the issuance size. Malaysia’s Ministry of Finance said the transaction helped maintain the government’s benchmark curve and provided an important pricing reference for Malaysian companies and related entities raising capital in international markets.
The Philippines is another notable example of adjusting issuance size to market conditions. In January 2026, the country raised $2.75 billion across three maturities of 5.5, 10, and 25 years. In June, the Philippines returned to the market with a $2.5 billion issuance, up from an initial target of $2 billion after the order book reached 4.4-times the target. The transaction comprised 5.5-year and 10-year bonds as well as a tap of its 2051 bonds. Yields were 4.699 per cent, 5.355 per cent, and 5.850 per cent, respectively.
These transactions show that planning an international issuance requires simultaneous consideration of funding needs, maturity structure, the ability to create liquid benchmark points, and market conditions at the time of issuance.
Factors to consider
The cost of issuing USD-denominated bonds will depend primarily on US Treasury yields, the sovereign risk premium, and issuance costs. The 10-year US Treasury yield has recently approached 5 per cent, keeping the cost of USD funding in international markets elevated. For emerging economies, costs are also affected by credit and currency risk premiums. The OECD has noted that USD borrowing costs for emerging market economies have risen significantly in recent years. Therefore, any issuance decision should be considered as part of a broader public debt management strategy, rather than based solely on the nominal cost at the time of the transaction.
Strengthening sovereign credit quality is particularly important in a “higher-cost money” environment. International investors will assess the overall outlook for growth, fiscal conditions, public debt, the external balance, and the stability and transparency of policies. Vietnam is currently rated BB+/Stable/B by S&P Global Ratings, according to its latest published information. Maintaining macro-economic stability, improving transparency, strengthening public debt management, and deepening engagement with credit rating agencies and international investors could therefore contribute to better funding conditions.
The timing of an issuance should also remain flexible. An NDR without a bond offering allows the government to update investors, maintain investor relationships, and gauge market appetite.
In terms of issuance structure, Vietnam could consider anything from a single benchmark bond with a medium-to-long maturity to two or more maturities as it gradually builds a benchmark yield curve. The objective is to balance cost, size, maturity, liquidity, and investor quality. For a first transaction after a prolonged absence from international markets, attracting long-term institutional investors with a geographically diversified base will be especially important for secondary market liquidity and benchmark formation.
Vietnam could also consider issuing a green or sustainability bond as part of its first transaction. Brazil’s experience shows that USD-denominated sovereign sustainability bonds can form part of an international funding strategy. In November 2025, the country issued a $1.5 billion seven-year sustainability bond at a yield of 5.5 per cent. However, green and sustainability structures typically entail higher requirements for the use-of-proceeds framework, eligible expenditure, reporting, and impact assessment.
Key areas of action
Overall, the success of an international bond issuance should be measured not only by the amount of capital raised and the cost of funding but also by investor diversification, the participation of long-term investors, secondary market liquidity, the bond’s ability to serve as a reference for Vietnamese companies, and the potential to reuse the resulting curve in subsequent issuances.
Based on international experience and the analysis above, Vietnam could consider a preparation program built around five areas.
First, proactively complete all preparations so that an issuance can be launched when market conditions are favorable. Vietnam should complete key work in advance, including the legal structure, credit rating, selection of advisers, preparation of offering documents, and engagement with appropriate investor groups. When market conditions are favorable, advance preparation would shorten the time between the issuance decision and execution while increasing the ability to capture appropriate funding costs.
Second, establish a regular international investor relations program. Periodic updates on macro-economic conditions, fiscal policy, public debt, the balance of payments, and institutional reforms would help reduce information asymmetry.
Third, treat the sovereign credit rating as part of the capital-raising strategy. Improving sovereign credit quality would not only benefit the government but could also have spillover effects on the cost of capital for Vietnamese companies and banks.
Fourth, select underwriters based on their ability to reach and distribute bonds among investors. When selecting underwriters for an international issuance, the decision should not be based solely on service fees. It should also consider their access to international investor groups, ability to build a diversified order book, and capacity to support trading and liquidity after issuance. This would be particularly important for a transaction intended to establish a benchmark bond in international markets.
Fifth, design the transaction with the objective of building a benchmark yield curve. The size, maturity, and structure should be selected so that the bond has the potential to trade actively and serve as a reference. A large bond with limited liquidity would be less effective in fulfilling this function.
Overall, the success of an international bond issuance should be measured not only by the amount of capital raised and the cost of funding but also by investor diversification, the participation of long-term investors, secondary market liquidity, the bond’s ability to serve as a reference for Vietnamese companies, and the potential to reuse the resulting curve in subsequent issuances.
Vietnam’s potential return to the USD bond market would therefore represent a step in a broader strategy to rebuild the “railway” connecting the country’s capital markets with global investors.
(*) Hong Ha is an Independent Expert.
 Google translate