

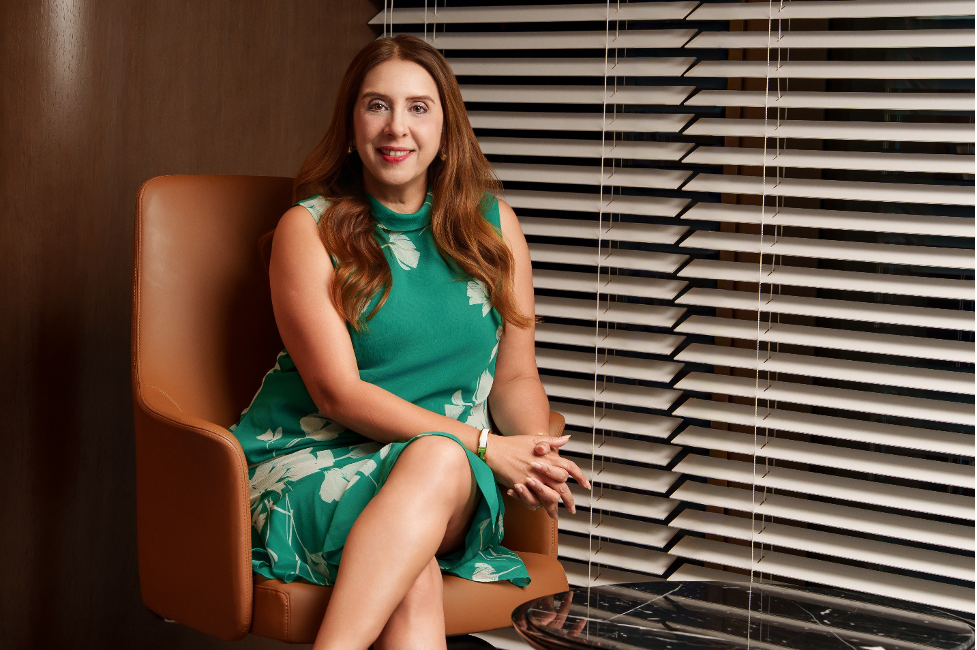
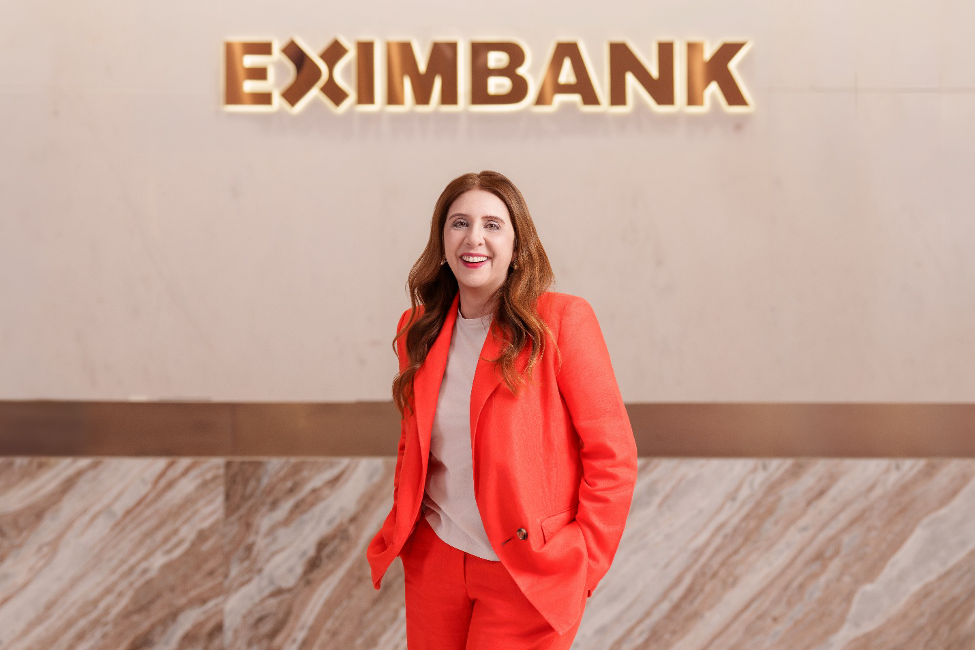
Ms. Richa Goswami, Member of the Board of Directors at Eximbank, sees that tension at the heart of the bank’s next chapter. Her view is not that Eximbank should leave its past behind, but that it should recover what made the bank relevant in the first place and reinterpret it for customers whose lives, expectations and choices have changed.
For her, the past offers a foundation, not a blueprint for the future.
That idea runs through her approach to transformation. Growth is not simply about adding technology, launching more products or following what other banks are doing. It starts with purpose, sharp choices about where to compete, and an understanding of what customers now value. Technology, culture and governance then have to work together to deliver it.
Across the conversation, three ideas recur: purpose, relevance and trust.
Rediscovering purpose, not reinventing it
Ms. Goswami sees a clue to Eximbank’s future in the bank’s own beginnings.
Established as the Export-Import Bank to serve Vietnam’s importers, exporters and businesses as the country entered a new era of growth, Eximbank was built around a practical purpose. Ms. Goswami points to stories of employees staying up late, answering phones, sending faxes and doing whatever it took to support customers.
To her, that was customer-centricity before the term entered the management lexicon. The opportunity now is not to recreate those old ways of working, but to recover the intent behind them.
“What pulls me most toward this moment is Eximbank’s own history,” she said. “That is customer-centricity. That’s the DNA this bank was actually built on.”
Purpose, in this sense, is more than a brand statement. It provides continuity through change: a way to decide what should remain constant even as products, technology, operating models and customer expectations evolve.
Eximbank’s original customers were businesses participating in Vietnam’s growth story. Today, the context, technology and expectations are different. But the underlying question remains: how can the bank be genuinely useful to the people and businesses it exists to serve?
For her, that is where the next phase begins.
Eximbank’s original customer-first spirit is not something to recreate, but to reinterpret for a new generation.
Relevance has to be earned again
History, however, is not a strategy. What worked in the past does not stay relevant simply because it once worked well.
“The truth is our customers have changed,” she said.
The observation is simple; the implications are not. Banks have traditionally built products and then found ways to sell them. Ms. Goswami argues for reversing that order: understand how customers live, where friction sits in their financial lives, what they value and what they now consider normal - then decide what the bank should build. As she puts it: “People don’t pay for products, they pay for experiences.”
That shift matters particularly in Vietnam, where a large younger generation expects services to be personalized, relevant and immediate. She sees an opportunity for a fast-growing market to learn from digital disruptors elsewhere and leapfrog rather than follow the same path step by step.
Her broader experience has also reinforced a practical instinct: treat constraints as a source of focus, challenges as opportunities, and transformation as a discipline of choosing what matters most.
For Eximbank, that means translating customer insight into a small number of choices the organization can execute exceptionally well.
Relevance is not created by trying to be everything to everyone. Ms. Goswami argues for what she calls “ruthless prioritization”: know which customers you want to serve, identify the experiences that matter most to them, and focus execution on the few priorities that can genuinely move the needle.
“In life, less is more,” she said.
It is depth over breadth: solve meaningful pain points, create genuine reasons for customers to choose the bank and resist confusing activity with progress.
Trust is earned through experience, not messaging
If purpose explains why an institution matters and relevance determines whether it continues to matter, trust determines whether the relationship can endure. In banking, Ms. Goswami sees trust as particularly personal - and ultimately more valuable than any single financial metric.
Money is not an abstract product. It represents work, sacrifice, plans and responsibilities. When customers place it with a financial institution, they are entrusting that institution with something deeply connected to their lives.
For Ms. Goswami, customer trust begins with a simple test: do people feel listened to, understood and confident that the bank will act on what matters to them? In her view, financial ratios may matter to bankers, but customer trust is the asset that makes a relationship sustainable.
That trust is accumulated through repeated experiences: whether everyday banking works, whether the bank listens and responds, whether customers feel understood at important moments, and whether the institution creates value rather than simply selling another product.
That is why she rejects the idea that customer experience is merely a layer of service or communication around a product-led organization.
Her framing is more human: banking is a personal business, and institutions have to treat people with empathy, care and respect. That changes how transformation should be judged.
Some interactions should become almost effortless. Ms. Goswami recalls seeing account opening at a traditional bank take weeks while digital challengers could complete it in minutes. Fixing that kind of friction is not simply a technology project: it can require changes across operations, compliance, risk and legacy systems. The point is not digitalization for its own sake, but making everyday banking fast, secure and dependable.
Other moments demand something different. She recalls how recently widowed customers sometimes contacted a bank with little understanding of their finances. In those moments, the right response was not simply a more efficient process, but people trained to listen with empathy before moving to financial solutions. Technology can remove friction; human judgement and care still matter when life becomes complicated.
The choice, then, is not digital versus human. It is about using each where it creates the right experience for the customer.
Technology should follow strategy
This is why Ms. Goswami is wary of equating transformation with technology. AI, digital platforms and new capabilities create enormous possibilities. But buying technology before deciding which customer problem to solve risks turning transformation into a race for novelty.
“Technology is an enabler, not the starting point. The tail can’t wag the dog,” she said.
The starting point is strategy. On this, she is direct: transformation only creates value when the strategy starts with the customer, identifies the problems worth solving and makes clear choices about where the bank intends to differentiate.
Governance creates discipline. Technology adds speed and capability. Execution turns choices into outcomes. But discipline cannot compensate for choosing the wrong target. As Ms. Goswami argues, everything else creates value only after the organization is clear about what it is trying to solve for the customer.
The same logic applies to data. Banks hold vast amounts of customer information. The more important question, she argues, is what value customers receive in return.
Personal financial management tools offer one example. When data helps customers understand their spending, saving or financial behavior and make better decisions, information becomes useful. That can build a stronger relationship than one based only on rates or promotions.
Transformation starts inside the bank, too
There is another side to customer trust that customers may never see. An organization’s ability to deliver externally depends heavily on the environment it creates for its own people.
A transformation strategy can look compelling on paper and still fail if employees are not supported, empowered or equipped to execute it. Culture, in that sense, is not a soft issue; it is an execution issue.
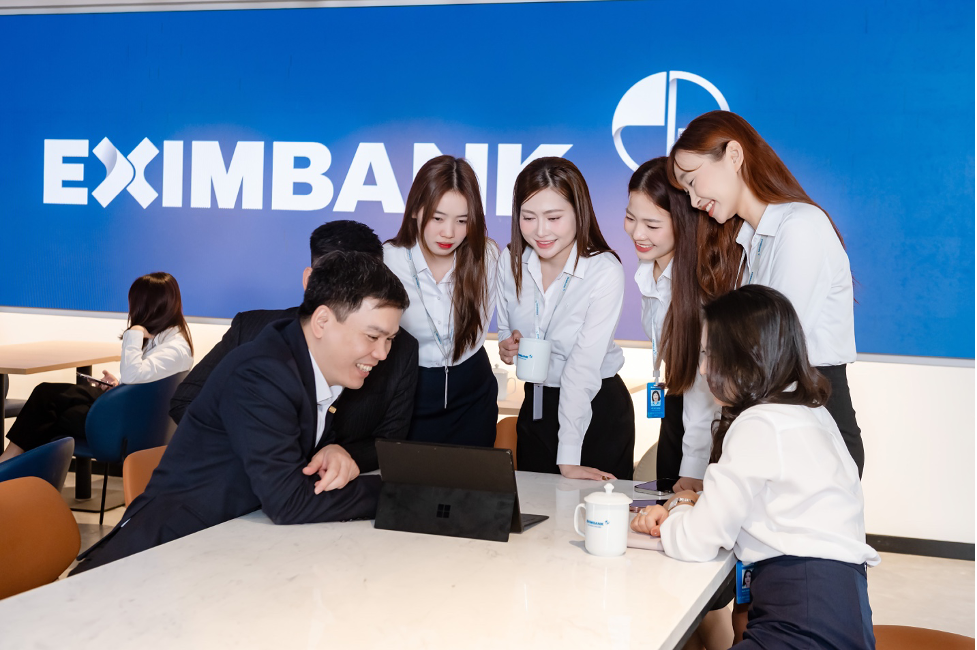
Ms. Goswami’s point is practical: employees need the confidence and support to act in the customer’s interest. Small acts of judgement and empathy can create disproportionate customer delight when people are trusted to make them.
At board level, that means keeping strategy anchored in customer outcomes, staying connected to the customer and employee reality behind management reports, and ensuring that technology and investment choices serve the strategy rather than drive it.
The principle is simple: customer signals have to travel into decision-making. Complaints, feedback and everyday friction are useful only if the organization acts on them.
As she puts it, transformation “starts and ends with the customer.” Understand the customer first; strategy follows, execution brings it to life, and governance keeps the organization on track.
Employee experience is part of the same system. People who feel supported and empowered are better placed to create the experience the bank wants customers to have. Strategy, culture, people, technology and governance all matter - but they have to pull in the same direction.
From transformation to rebuilding
Ms. Goswami’s ambition for Eximbank goes beyond improving individual processes. Over the next five to ten years, she wants Eximbank to become a brand that Vietnamese customers genuinely love, not simply use - a bank they trust, find convenient and feel truly understands their needs.
Her ambition extends beyond Vietnam. She wants Eximbank’s transformation to become a case others study alongside global banking benchmarks: evidence that a long-established institution can rebuild around customers and compete at a world-class standard.
Rebuilding does not require erasing history, but giving original purpose a new expression for a changed world. For Eximbank, that means leveraging its legacy of supporting growth while adopting new tools, capabilities, and execution discipline.
That ultimately defines Eximbank’s next chapter: preserve the purpose that gives the bank meaning, change what no longer creates relevance, and earn trust through everyday customer experiences.
 Google translate